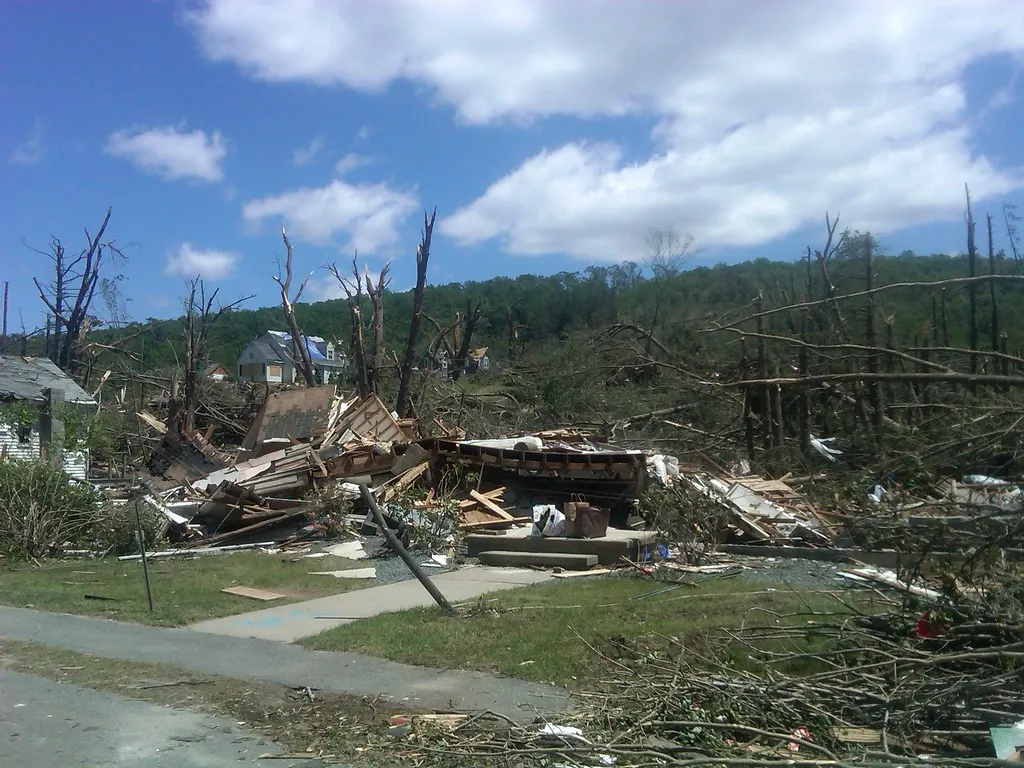
- Violent tornadoes
- Hail
- Straight-line wind
- Debris impact
A city defined by rebuilding
Moore has been struck by three major tornadoes in fourteen years. The May 3, 1999 Bridge Creek–Moore tornado produced F5 damage and crossed the city on its way toward south Oklahoma City and Midwest City. On May 8, 2003, another strong tornado followed a similar path, damaging many homes that had only just been rebuilt. Then on May 20, 2013, an EF5 tornado tore through Moore, destroying neighborhoods and striking the Plaza Towers and Briarwood elementary schools.
That history shapes how claims work here. Many owners know the process well, and so do carriers. Total losses go to policy limits, but the harder disputes often involve homes that were damaged rather than destroyed: shifted framing, cracked slabs, debris-pierced roofs and siding, and broken windows that a quick inspection can understate.
Housing old and new
Old Town Moore and the streets around it have 1960s and 1970s brick ranches with simple roofs and single-pane windows that have been replaced piecemeal over the years. In areas hit in 1999, 2003 and 2013, many homes were rebuilt to newer standards. After 2013, Moore adopted stronger building rules for new homes, including requirements aimed at better connecting roofs and walls to foundations. Those added costs can matter in a claim: if a repair has to meet current code, the difference is often covered under ordinance-or-law coverage, up to its limit.
Newer subdivisions on the east and south sides of town have larger two-story homes, storm shelters and safe rooms. Shelters damaged by debris or flooding are a part of the claim that adjusters sometimes forget.
Damage that’s easy to miss
Partial tornado damage is where the money gets lost. Debris strikes can puncture roofing and house wrap in places that only show from a ladder. Pressure changes can shift trusses or crack drywall throughout a house. Garage doors that buckled in high wind may have strained their tracks and framing. Our tornado and windstorm claim appraisal page lays out what a full inspection should include.
What to expect from appraisal
When the carrier accepts coverage but disputes the price, either side can usually invoke the appraisal clause. We inspect the whole house, including attic framing, slab and shelter, and price repairs with central Oklahoma costs at the time of loss and any code upgrades shown separately. If you want to check whether your claim is ready for appraisal, try the appraisal readiness check.
Moore at a glance
| County | Cleveland County |
|---|---|
| Housing mix | Moore mixes 1960s–1970s brick ranches in older sections, homes rebuilt after 1999, 2003 and 2013 to newer standards, and recent two-story subdivisions on the city’s east and south sides. |
| Neighborhoods & areas |
|
| Storms on record |
|
Services for Moore property owners
- Appraisal Representation
- Homeowners Claim Appraisal
- Commercial & HOA Appraisal
- Hail & Roof Damage Appraisal
- Tornado & Wind Appraisal
- Water & Pipe Leak Appraisal
- Fire & Smoke Loss Appraisal
- Ice Storm & Tree Damage
Moore questions
Does insurance pay for Moore’s stronger building code requirements?
If your policy includes ordinance-or-law coverage, the added cost of bringing a damaged home up to current code is often covered up to that coverage limit. We itemize code-required work separately so it can be reviewed against the right coverage.
My house wasn’t destroyed but the walls and ceilings cracked after a tornado nearby. Is that covered?
Damage caused by windstorm, including structural movement from high winds, is generally covered under homeowners policies. The dispute is usually over how much repair is needed. We inspect for framing movement, drywall cracks and slab issues and price the full repair.
Is my storm shelter part of my claim?
A shelter damaged by a covered peril is usually part of the dwelling or other structures coverage, depending on whether it’s attached. We include shelter repairs in our estimate.