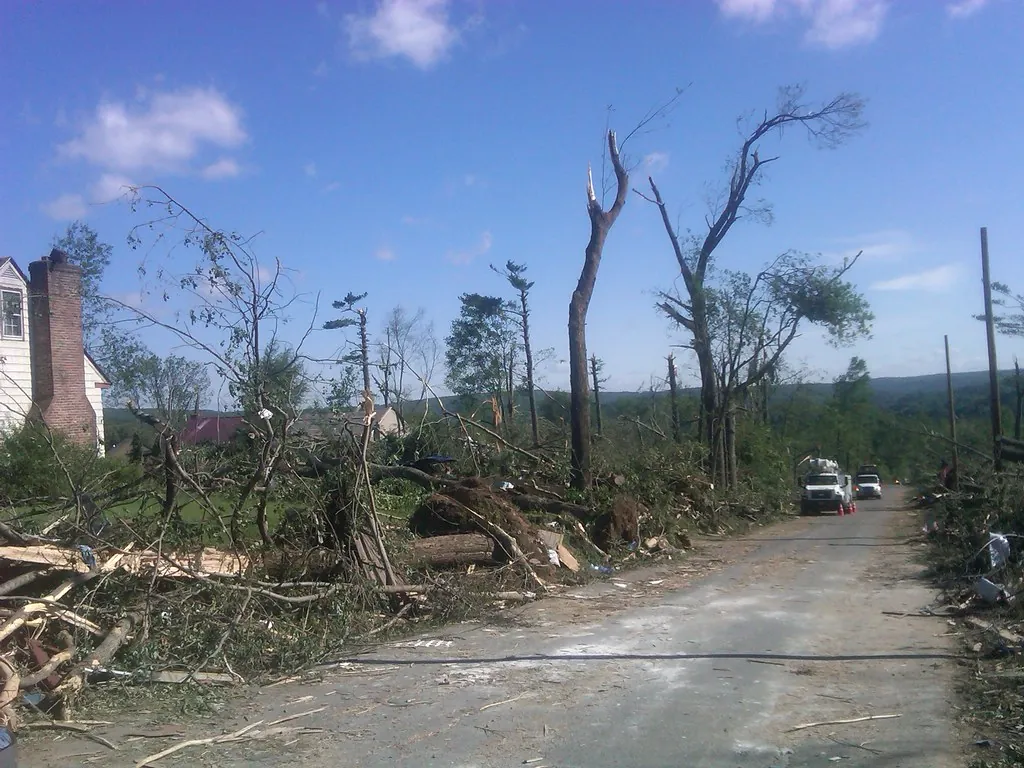
Oklahoma’s wind history shapes every claim
Few places know tornadoes like central Oklahoma. The May 3, 1999 Bridge Creek–Moore tornado and the May 20, 2013 Moore EF5 tornado reshaped how the metro builds and insures homes. The May 31, 2013 El Reno tornado was the widest on record. More recent storms, including the February 2023 Norman tornado, the April 2024 tornado that struck Sulphur and the May 6, 2024 Barnsdall tornado, show that damage can hit any part of the state and any time of year.
Straight-line winds from severe thunderstorms cause far more claims than tornadoes in a typical year, and they often get adjusted as minor roof repairs when the damage goes deeper.
Partial wind damage: where disputes start
Roofs and exteriors
- Creased or unsealed shingles that look intact from the ground but no longer resist wind.
- Lifted metal panels, loose fasteners and torn ridge caps.
- Siding, soffit and fascia blown off or cracked, and matching problems when replacing it.
- Fences, carports, patio covers and outbuildings.
Hidden structural damage
High winds can rack framing, shift trusses, pull anchor bolts and crack brick veneer ties. We look for drywall cracks, sticking doors and roofline deflection that point to movement, and we bring in an engineer when the structure needs that level of review.
Major and total losses
When a tornado destroys a home, the dispute moves to rebuild cost and limits. The panel may need to value demolition, debris removal, foundation repair or replacement, code upgrades, and the full rebuild at current Oklahoma labor and material prices, which often rise after a big event.
Policy terms that matter after a tornado
- Wind and hail deductible. Often a percentage of the dwelling limit. Use the percentage deductible calculator to see what you will absorb, and read our guide to percentage wind and hail deductibles.
- Replacement cost versus actual cash value. Many policies pay ACV first and release depreciation after repairs. The RCV and ACV holdback calculator shows that split.
- Ordinance or law coverage for code upgrades the city requires when you rebuild.
- Debris removal limits, which can run out fast on a destroyed home.
- Additional living expense while you are out of the house.
How we work a wind appraisal
Keep receipts for emergency tarping, board-up and fencing to keep pets or livestock in. Reasonable steps to protect the property from further damage are usually part of the covered loss.
Tornado claims also tend to involve many contractors at once. After a large event, roofers, framers and restoration crews from out of state arrive quickly, and prices can vary widely. We price the loss based on reasonable local costs for the work required, and we document why each line belongs in the scope so the panel can follow the reasoning.
We start with the policy and carrier estimate, inspect and document the full property, and price the loss line by line. For partial losses we focus on proving the scope; for total losses we focus on a complete, defensible rebuild estimate. Then we work the difference with the carrier’s appraiser and, if needed, the umpire. Keep a record of dates and deadlines with the claim timeline planner.
Available across Oklahoma
We take this work statewide, including Oklahoma City, Tulsa, Norman, Broken Arrow, Edmond, Lawton, Moore, Midwest City and every county in between.
Common questions
Is tornado damage covered by a homeowners policy?
Wind, including tornadoes, is a covered peril under most Oklahoma homeowners policies, usually subject to a wind and hail deductible. Flooding from the same storm is generally excluded and needs separate flood coverage.
What if the carrier says my roof was just old?
Wear and tear is usually excluded, so the dispute may involve both causation and scope. Appraisal can value storm damage, but a flat denial based on age is a coverage question you may need to take up separately.
Can appraisal include my debris removal costs?
Yes, if debris removal is part of the covered loss and your appraisal clause covers the full amount of loss. Payment is still capped by any debris removal limit in your policy.