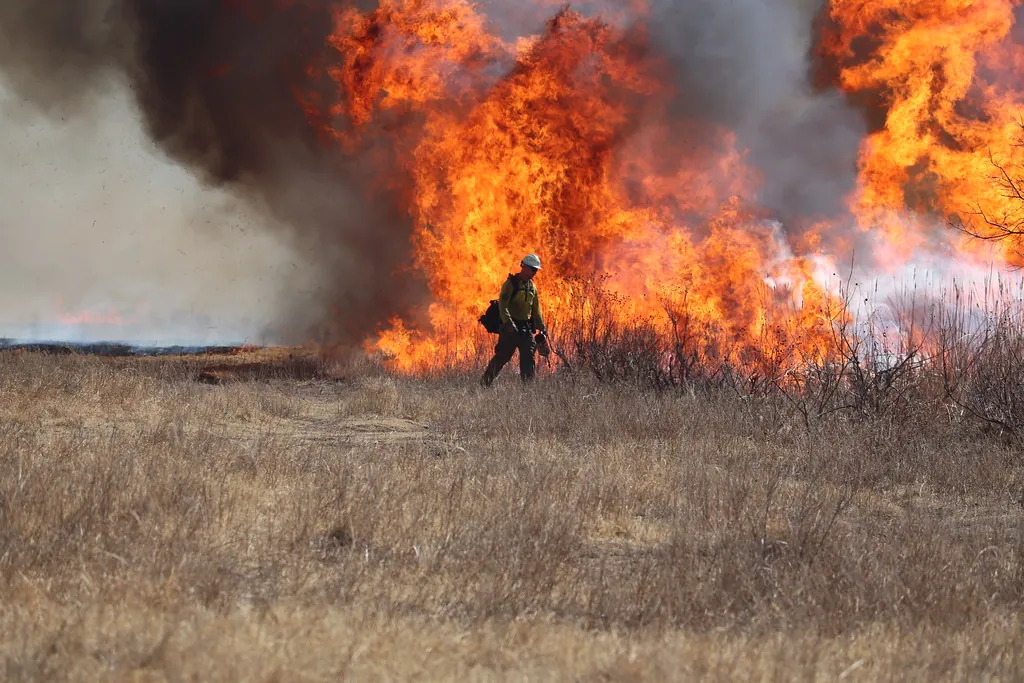
Fire risk on Oklahoma’s plains and prairies
Dry grass, strong wind and low humidity make late winter and early spring the main fire season in Oklahoma. The risk is highest in the Northwest and Panhandle, around Woodward and Guymon, and across the Southwest near Altus and Lawton, but grassfires also reach the Cross Timbers and the edges of the Oklahoma City and Tulsa metros. The 2017 northwest Oklahoma wildfires burned a vast area of ranchland and destroyed homes, barns, fences and livestock.
What a wildfire claim usually includes
Homes and outbuildings
Fire can destroy a home outright, or burn part of it and leave heavy smoke damage. On rural properties, barns, hay sheds, shops, well houses and equipment buildings are often hit too. Those usually fall under other structures coverage on a homeowners policy or under a separate farm or ranch form.
Fencing
Miles of barbed wire, pipe fence and corner posts can burn in one event. Fence claims are often underpriced because the carrier uses a low per-foot number that ignores terrain, brush clearing and the cost of skilled fence crews after a large fire.
Smoke damage to homes that did not burn
Homes near the fire line can be filled with smoke and ash. Cleaning, HVAC cleaning or replacement, and odor removal are often disputed.
Where wildfire appraisals split
- Rebuild cost in rural areas, where travel, crew availability and material delivery raise prices.
- Fence pricing per foot or per mile, including posts, braces, gates and clearing.
- Metal building replacement versus repair of heat-warped framing and panels.
- Smoke cleaning scope for homes near the fire.
- Debris removal of burned structures, which can exceed modest policy limits.
Before and during the appraisal
Gather photos of the property before the fire if you have them, receipts or records for fencing and outbuildings, and any county or fire department reports. Aerial images and older listing photos can help establish what was there. The appraisal readiness check helps you decide whether your dispute is ready for appraisal, and the holdback calculator shows how depreciation affects payment.
Rebuilding after a rural fire
Rebuilding on a rural property often takes longer than in town. Contractors may need to travel from Enid, Woodward or Lawton, materials may come from farther away, and permits, well and septic work, and electrical service all have to be coordinated. A fair valuation reflects those real costs instead of using city pricing.
Metal buildings deserve a close look. Heat can warp purlins, girts and panels even where the building did not collapse, and coatings may fail later. We document distortion and fastener damage so the panel can decide between repair and replacement on evidence, not guesswork.
Timing also affects actual cash value and holdback. If your policy pays depreciation only after you rebuild, check for any deadline to complete repairs. If you need more time, ask the carrier in writing before that deadline passes. Keep records of every step so the holdback can be released when the work is done.
We inspect the property, measure fencing and buildings, and build a complete valuation using rural Oklahoma pricing. Then we work the differences with the carrier’s appraiser and, if needed, present the rest to the umpire. For a closer look at how panels resolve disputes, see inside an umpire hearing.
Available across Oklahoma
We take this work statewide, including Oklahoma City, Tulsa, Norman, Broken Arrow, Edmond, Lawton, Moore, Midwest City and every county in between.
Common questions
Is wildfire covered by a homeowners policy?
Fire, including wildfire and grassfire, is a covered peril under most homeowners and farm policies. Limits for other structures, fencing and debris removal vary, so check your declarations page.
Can appraisal value miles of burned fence?
Yes, if fencing is covered under your policy. The panel can decide the length, type and cost to replace it, subject to any fencing limit in your policy.
What about livestock and hay lost in the fire?
Those are usually covered only under a farm or ranch policy that schedules them. If they are covered and the dispute is about value, they can be part of the appraisal.