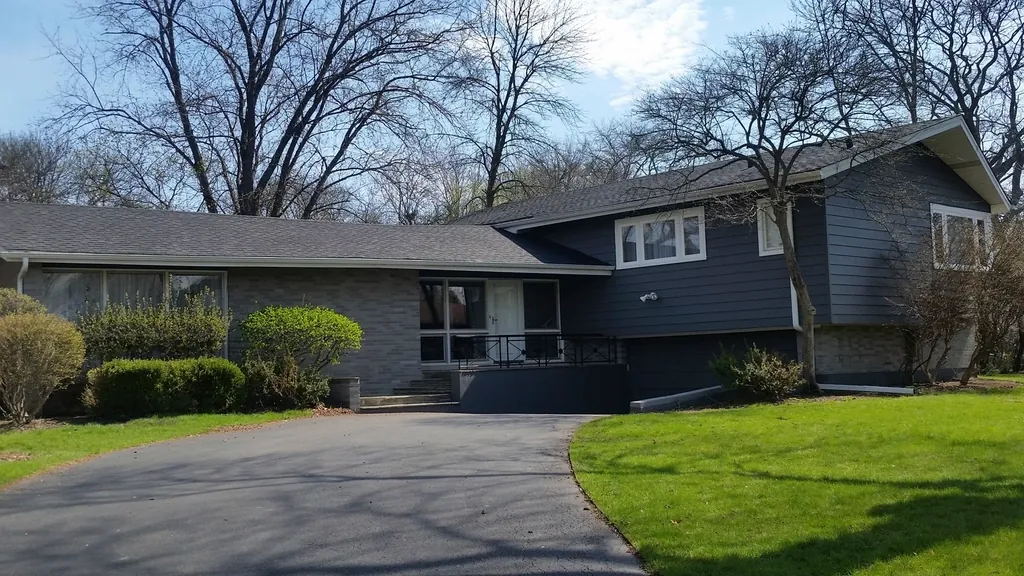
The homes we see most often
Oklahoma housing has a few strong patterns, and each one creates its own kind of claim dispute.
Brick ranch homes
Single-story brick veneer ranches built from the 1960s through the 1990s fill neighborhoods in Midwest City, Del City, Norman and Broken Arrow. Hail rarely hurts the brick, but it hits gutters, window wraps, garage doors, fascia and wood trim hard. Those smaller line items add up and are easy to leave out.
Newer suburban builds
Two-story homes in Edmond, Yukon, Owasso and Jenks often mix brick, stone and fiber-cement siding with steep, cut-up roofs. Pitch, valleys and layering drive roof costs, and a few degrees of pitch or a missed ridge line can move an estimate by a meaningful amount.
Rural and older homes
Farmhouses near Enid, Woodward and Guymon, and older pier-and-beam homes in towns like Muskogee and McAlester, bring outbuildings, metal roofs, well houses and detached shops into the claim. Those often fall under “other structures” coverage with its own limit.
Where homeowner claims usually stall
- Repair versus replace on the roof. The carrier approves a few squares; you and your roofer see damage on every slope.
- Matching. Discontinued shingles, siding profiles and interior finishes that cannot be blended without a visible difference.
- Roof payment schedules. Many Oklahoma policies pay roof surfaces on a schedule tied to roof age, which shrinks the check on older roofs. Our roof payment schedule calculator shows how that math works.
- Code items and permits. Drip edge, ice-and-water barrier and decking requirements that vary by city.
- Overhead and profit. Whether a general contractor is reasonably needed to coordinate several trades.
Impact-resistant roofs and what they change
Many Oklahomans have moved to UL 2218 Class 4 impact-resistant shingles, and many carriers give a premium credit for them. Ask your agent what credit applies on your policy. Those roofs still take damage in severe hail, but carriers sometimes argue that marks on them are cosmetic. We document granule loss, fractured mats and damaged accessories carefully so the panel sees function, not just appearance.
How we approach a homeowner appraisal
We start with your policy and the carrier’s estimate, then inspect the whole property, not just the area the adjuster flagged. Interior damage from a leak, a cracked skylight, a dented storm shelter door or a crushed fence can be part of the same claim. We build a line-item valuation, meet the carrier’s appraiser, and work the differences down. If an umpire is needed, we present what is left with photos and measurements.
What you can expect from us
We return calls, explain each step before it happens, and send you our valuation before we meet the carrier’s appraiser so nothing in it surprises you. If we think the carrier’s number is close to fair, we say so. Appraisal costs money, and it only makes sense when the gap is real and the evidence supports it.
We work statewide, from the Oklahoma City and Tulsa metros to smaller towns in Kiamichi Country and the Southwest. See the cities we serve for local notes on common building types and storm history.
If you are not sure whether your dispute fits appraisal, start with how the appraisal process works or get in touch with your policy and estimate.
Available across Oklahoma
We take this work statewide, including Oklahoma City, Tulsa, Norman, Broken Arrow, Edmond, Lawton, Moore, Midwest City and every county in between.
Common questions
Do I need a public adjuster or an appraiser?
They are different roles. A public adjuster handles the claim on your behalf from the start; an appraiser serves on the appraisal panel once appraisal is invoked to resolve the amount of loss. We work only as appraisers.
Will appraisal cover my detached shop or fence?
If those structures are covered under your policy, typically as other structures, the panel can value their damage too. Their payment is still limited by the coverage limit stated on your declarations page.
Can appraisal help if my roof was paid on a schedule?
Appraisal can settle the replacement cost and the scope of damage. How a roof payment schedule applies is a policy question, so we review the endorsement before telling you what appraisal is likely to change.